Fake store chargeback evidence checklist and dispute packet
November 17, 2026
A fake online store may take your payment, deliver a different item or disappear before your order arrives. If you paid by card, organized evidence can help your bank assess a dispute. Here's what to save, what to tell your provider and how to build a packet without uploading private details.
Key takeaways
- Save receipts, product listings, delivery promises and seller correspondence before they disappear
- Describe the true problem: non-receipt of goods is different from a payment you never authorized
- Ask your card issuer about deadlines promptly; bank transfers, crypto and gift cards need different recovery routes
- The offline builder creates an evidence inventory, cover note and timeline, but can’t submit a claim or guarantee repayment
What counts as fake store chargeback evidence?
Fake store chargeback evidence shows what you purchased, what the seller promised and what happened. It may support a card dispute for undelivered, misdescribed or unrefunded goods. Your issuer decides whether the claim qualifies.
Fake storefronts can copy branding, promote unrealistic discounts and use misleading tracking details. The US Federal Trade Commission warns that shoppers may receive counterfeit goods, the wrong item or nothing. Before paying, independently verify the business and exact website address; HTTPS alone proves little about legitimacy.
Collect these records before they disappear
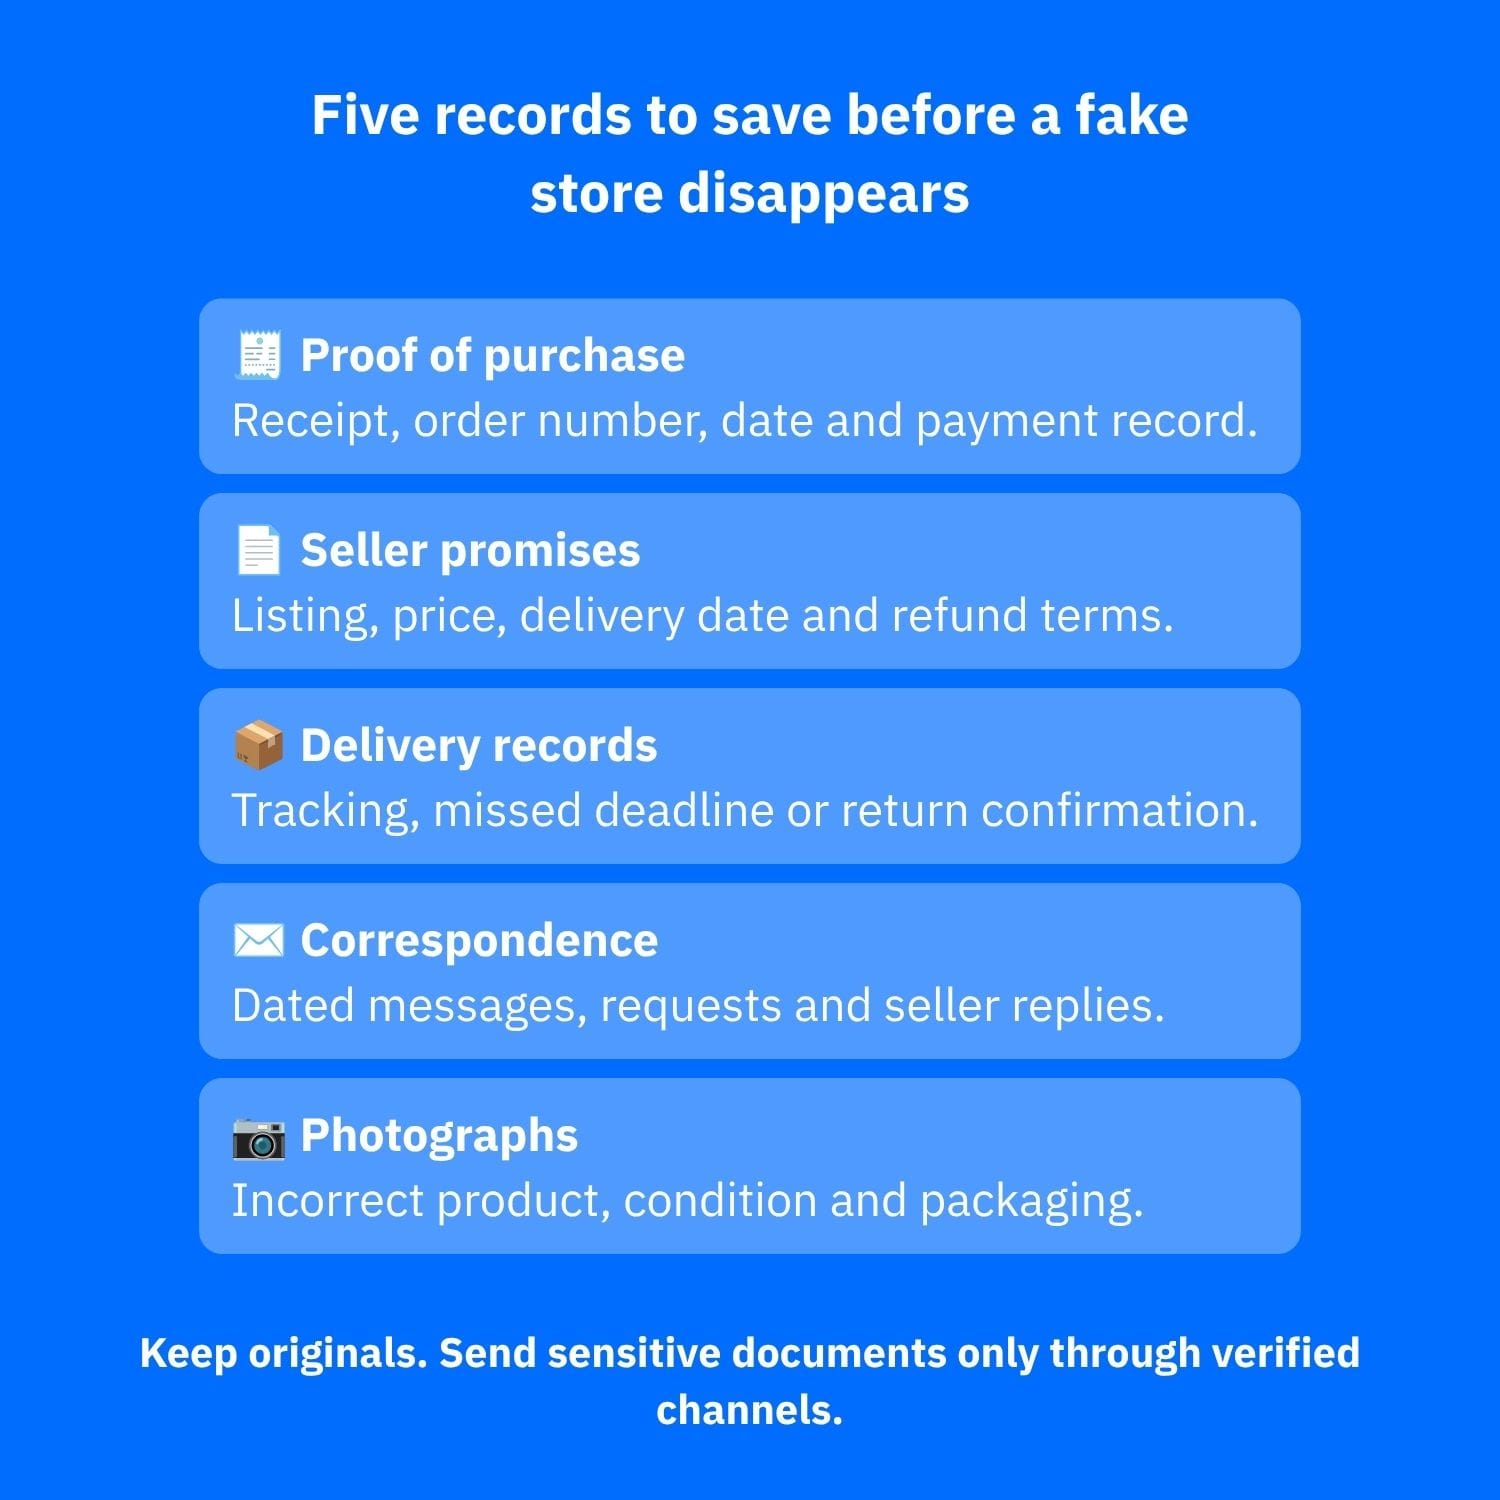
Save originals in a folder, keeping dates and URLs visible. Avoid sharing payment credentials or identity documents publicly. Collect:
- Purchase proof: receipt, order number, date, amount and payment entry from the official banking app
- Seller promises: product listing, URL, price, delivery deadline and refund terms
- Delivery records: tracking, missed delivery date, cancellation or return confirmation
- Correspondence: dated refund or delivery requests, seller replies and failed contact attempts
- Photos: item and packaging, particularly when goods are wrong, defective or apparently counterfeit
The FTC recommends keeping purchase and communication records. Never invent missing dates or recreate supposed evidence. Our scam evidence checklist covers other fraud scenarios.
Match your complaint to the payment method
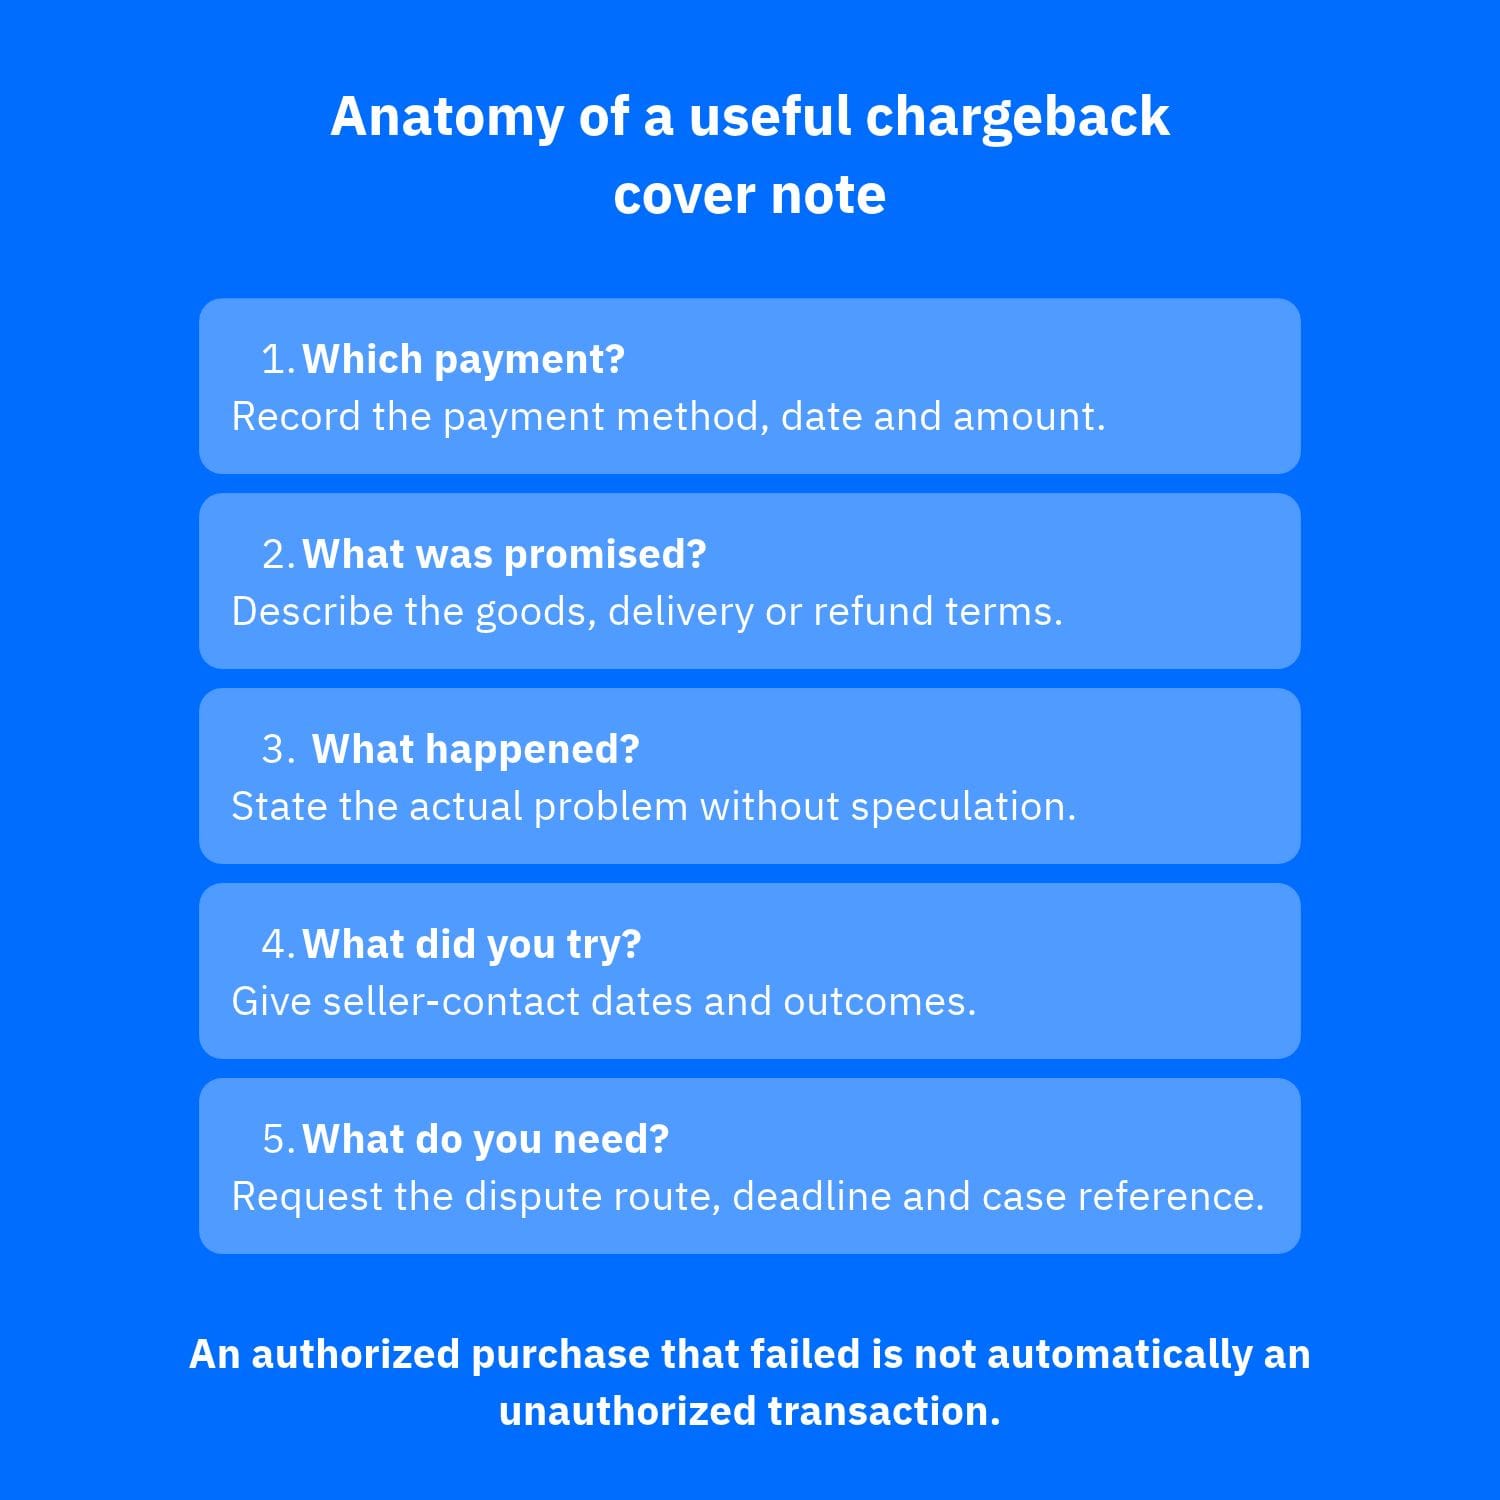
A chargeback asks a card issuer to challenge a transaction under applicable card-network rules. If you approved the purchase but received nothing, report non-delivery, not an unauthorized transaction. A payment you never approved needs immediate attention from the issuer's fraud team.
Debit and credit cards may carry different protections. With Apple Pay or Google Wallet, contact the issuer of the underlying card. With PayPal or marketplace checkout, examine the provider's dispute process. A bank transfer calls for an urgent recall request, not a card chargeback. See our guide to money sent by bank transfer.
Build a packet the bank can assess
Write a cover note stating the purchase, actual payment method, delivery or refund promise, failure and seller-contact dates. Attach records chronologically. Ask the provider for its dispute category, deadline, evidence requirements and case number.
Our offline fake-store packet builder prepares tailored actions, an evidence inventory, a factual draft and a printable timeline for US, UK, EU, Romanian and Spanish readers. Selections stay on your device, with no financial identifiers requested. It neither verifies stores nor files chargebacks.
Deadlines vary by country and claim type
In the US, certain credit-card billing-error claims require written notice within 60 days of the first statement showing the error; quality disputes differ. See the CFPB.
In the UK, chargeback deadlines are often around 120 days, depending on the circumstances. Qualifying credit-card purchases may also have Section 75 protection. See the Financial Ombudsman.
EU consumer rights differ from card-network procedures. Spain's Banco de Espana cautions that authorized purchases are not automatically reversible. Contact your provider promptly.
If you also exposed personal information
Report unauthorized payments through a verified bank contact. If card details were exposed, ask about blocking or replacing the card. Change compromised passwords from a trusted device. If you installed software or gave out remote access, avoid banking on that device until it has been assessed.
Report suspected fraud to your local authority. If a refund request is rejected, ask for reasons and review our bank-refusal escalation guide for more comprehensive instructions. Our financial scams hub covers more recovery routes.
How Bitdefender can help
Bitdefender Scamio assesses suspicious messages and links; Ultimate Security provides malware and phishing protection. For exposed credentials or personal data, SecurePass helps manage passwords and Digital Identity Protection monitors exposure. None guarantees payment recovery.
Conclusion
Accurate records and a truthful dispute category matter more than accusations. Save your proof, contact the correct provider and check the deadline. The packet builder organizes your case; the institution decides its outcome.
Frequently asked questions (FAQs)
What evidence do I need for a chargeback?
Usually an order receipt, payment entry, product listing, delivery or refund promise, and dated seller correspondence. Add tracking for undelivered goods or photos for products that differ from their description. Your issuer may require more, so request its checklist before submitting documents through a verified channel.
Do banks really investigate chargebacks?
Yes. Banks assess the claim and evidence; the merchant may respond through the card scheme. The result depends on the dispute reason, applicable rules and records. A provisional credit can be reversed, and filing a dispute does not ensure a refund.
Is a false chargeback illegal?
Knowingly lying to obtain a refund can constitute fraud, with consequences varying by jurisdiction. An unsuccessful good-faith claim is not automatically fraudulent. If you approved the purchase but received nothing, describe non-delivery rather than falsely reporting an unauthorized charge.
tags
Author
Vlad's love for technology and writing created rich soil for his interest in cybersecurity to sprout into a full-on passion. Before becoming a Security Analyst, he covered tech and security topics.
View all postsYou might also like
Bookmarks
